विषयसूची
- 01Business tax in Nepal
- 02Quick answer
- 031. Register the taxpayer correctly
- 042. Understand the income-tax base
- 053. Determine whether VAT applies
- 064. Withhold TDS correctly
- 075. Follow the filing calendar
- 086. Maintain defensible records
- 097. Manage related-party and cross-border risks
- 108. Prepare for assessment and tax clearance
- 11Practical checklist
- 12Legal update
छिटो जवाफ
A Nepal business generally needs correct PAN and VAT registration, reliable accounts and invoices, timely VAT and e-TDS filings, estimated income-tax payments where applicable, and an annual income return. Rates and concessions must be checked under the Finance Act for the relevant income year.
मुख्य तथ्यहरू
- ✓Income tax, VAT and TDS are separate but connected compliance systems.
- ✓Corporate income tax is generally based on taxable profit, subject to statutory adjustments.
- ✓Nepal applies a 13 percent standard VAT rate, with exempt and zero-rated supplies treated differently.
- ✓The IRD generally requires VAT and e-TDS compliance within 25 days after the relevant period.
- ✓Rates, thresholds and incentives can change through the annual Finance Act.
- ✓Consistent invoices, ledgers, contracts and reconciliations are essential for audit defence.
Business tax in Nepal
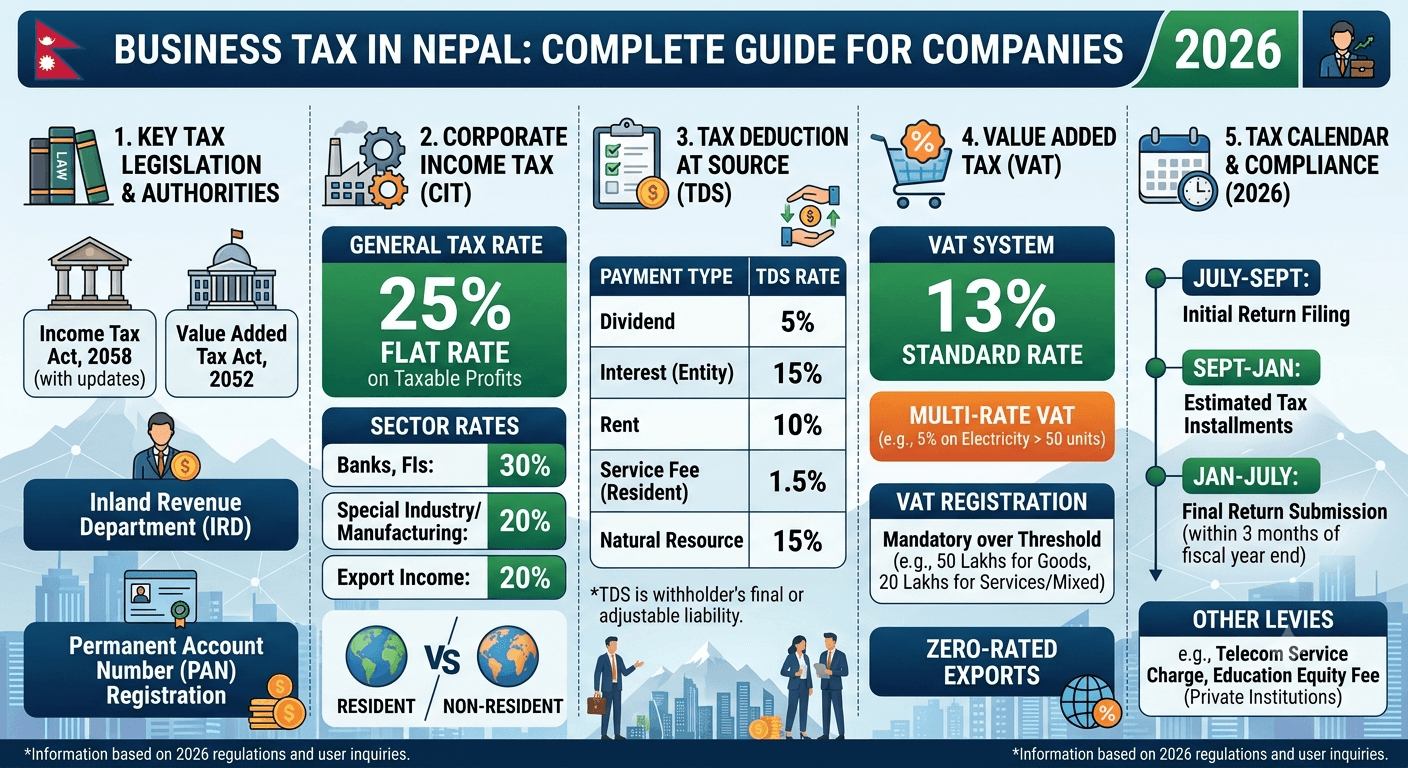
Businesses operating in Nepal may have several connected tax obligations rather than one single "business tax." The usual framework includes income tax on taxable profit, value added tax on taxable supplies where registration applies, tax deduction at source on specified payments, and procedural duties such as invoicing, record keeping, returns, estimated instalments and tax clearance.
The principal federal laws are the Income Tax Act, 2058 and the Value Added Tax Act, 2052, together with their rules and the annual Finance Act. Customs, excise, provincial and local taxes may also apply depending on the transaction. Because the Finance Act can change rates, thresholds, exemptions and concessions each year, a company should confirm the rule for the relevant income year rather than copying an old rate table.
Quick answer
A Nepal company should obtain the appropriate PAN and, where required, VAT registration; keep transaction-level books and valid invoices; deduct and deposit TDS on applicable payments; file periodic VAT and e-TDS returns; pay estimated income tax instalments when applicable; and submit its annual income return with supporting financial information. The exact tax rate depends on the taxpayer, activity, source of income and current Finance Act.
1. Register the taxpayer correctly
A company is a separate taxpayer from its shareholders and directors. Tax registration should match the company's exact legal name, registration number, registered address and business activities. The PAN is the identifier used for income-tax administration. VAT registration is an additional registration for businesses that meet a compulsory-registration rule or qualify and choose to register voluntarily.
Update the Inland Revenue Department when registered particulars change. A mismatch between company records, bank information, invoices and tax registration can delay filings, withholding credits and tax-clearance work.
2. Understand the income-tax base
Corporate income tax is generally imposed on taxable income, not simply on turnover. Accounting profit is the starting point, but tax law determines which income is included, which expenses are deductible, the timing of recognition, depreciation treatment, loss relief and adjustments for related-party or cross-border transactions.
Do not assume every accounting expense is tax deductible. The business should retain invoices, agreements, payment proof, payroll records and an explanation of the commercial purpose. Private expenditure, unsupported costs, capital items treated as immediate expenses and payments made without required withholding can create adjustments.
The applicable entity rate is not universal. General companies and specially regulated or incentivised sectors may be treated differently, and concessions can have detailed eligibility conditions. Confirm the current schedule before forecasting tax.
3. Determine whether VAT applies
VAT is a transaction tax distinct from income tax. A business may be profitable but outside compulsory VAT registration, or loss-making while still required to collect VAT. The current statutory standard rate is 13 percent, while exempt and zero-rated supplies receive different treatment.
The IRD has described general registration thresholds of NPR 5 million for taxable goods and NPR 1 million for taxable services. Mixed activities, specified businesses, imports, digital services, statutory changes and compulsory-registration rules require separate checking. Turnover should be monitored continuously rather than only at year end.
4. Withhold TDS correctly
Chapter 17 of the Income Tax Act requires withholding on specified payments. Common categories can include employment income, service fees, interest, rent, commission, royalties, contract payments and payments to non-residents. The payer normally deducts tax when making or accounting for the payment, pays the net amount to the recipient and deposits the withheld amount for that recipient.
Classification matters because rates and final-credit treatment differ. Check the recipient's residence, PAN, VAT status, legal form, payment character and any tax-treaty position before selecting a code. The IRD states that e-TDS details and payment are generally due within 25 days after the end of the month of payment.
5. Follow the filing calendar
Build a compliance calendar covering VAT periods, monthly e-TDS, payroll withholding, estimated tax and the annual income return. The IRD states that VAT returns are generally filed within 25 days after the end of the tax period. It also identifies estimated-tax instalment milestones at the end of Poush, Chaitra and Ashadh for taxpayers subject to instalments.
The annual income-tax return and self-assessed tax are generally due within three months after the end of the income year, subject to the Act and any valid extension. Do not rely on a calendar date copied from another year without converting the applicable Nepali date and checking an IRD notice.
6. Maintain defensible records
Keep sales and purchase invoices, ledgers, bank statements, contracts, import documents, payroll, fixed-asset records, withholding certificates, return acknowledgements and payment vouchers. Reconcile sales to VAT returns, expenses to TDS filings, payroll to employment withholding and tax balances to the general ledger.
Digital records should be backed up and traceable to the original transaction. A tax return is stronger when each material number can be followed from the filed form to the ledger and source evidence.
7. Manage related-party and cross-border risks
Transactions with shareholders, directors, group companies and foreign affiliates require arm's-length support. Cross-border payments may involve source rules, withholding, treaty relief, permanent-establishment questions, foreign-tax credits, transfer pricing, VAT on imported services and foreign-exchange documentation.
An invoice from abroad does not by itself determine the Nepal tax result. Review the contract, location of performance, rights supplied, recipient, beneficial owner and payment route before remittance.
8. Prepare for assessment and tax clearance
Before seeking tax clearance, reconcile all income-tax, VAT, TDS and other outstanding returns and payments. An IRD query should be answered against the notice, period and issue raised, with a document index and reconciled computation. Preserve submission evidence.
Tax planning means applying lawful choices before a transaction, not inventing evidence afterward. Review major contracts, financing, dividends, asset sales, reorganisations and foreign payments before execution.
Practical checklist
- Confirm PAN, VAT and registered particulars. - Map every revenue stream and major payment to its tax treatment. - Use valid invoices and preserve transaction evidence. - Reconcile and file VAT and e-TDS on time. - Forecast estimated tax and annual income tax. - Review related-party and cross-border transactions early. - Reconcile all filings before requesting tax clearance.
Legal update
This guide was reviewed on 21 July 2026. It explains the durable compliance framework and does not promise that a rate, threshold or concession will remain unchanged. Always check the Finance Act, amended legislation and current IRD notices for the relevant income year.
सामान्य प्रश्नहरू
बारम्बार सोधिने प्रश्नहरू
आधिकारिक स्रोतहरू
यो मार्गदर्शनको कानुनी समीक्षाका लागि प्रयोग गरिएका प्राथमिक सामग्री।
- 1.Inland Revenue Department - Income Tax Act, 2058, amended through Finance Act 2082पहुँच गरिएको २०२६ जुलाई २१
- 2.Inland Revenue Department - Income Tax Act, 2058, English textपहुँच गरिएको २०२६ जुलाई २१
- 3.Inland Revenue Department - Taxpayer FAQsपहुँच गरिएको २०२६ जुलाई २१
व्यावसायिक सहयोग
व्यावसायिक कानुनी सहयोग चाहिन्छ?
तपाईंको विषय, कागजात र अनुपालन आवश्यकता अनुसार अधिवक्ता-नेतृत्वको मार्गदर्शन प्राप्त गर्नुहोस्।
सम्बन्धित कानुनी सेवा हेर्नुहोस् →सम्पादकीय तथा कानुनी समीक्षा
समीक्षक: Wakil Nepal Legal Team
अन्तिम समीक्षा: २०२६ जुलाई २१
यो मार्गदर्शनले सामान्य कानुनी जानकारी प्रदान गर्छ। प्रक्रिया र आधिकारिक आवश्यकता परिवर्तन हुन सक्छन्, र विषय-विशेष सल्लाह आवश्यक हुन सक्छ।